
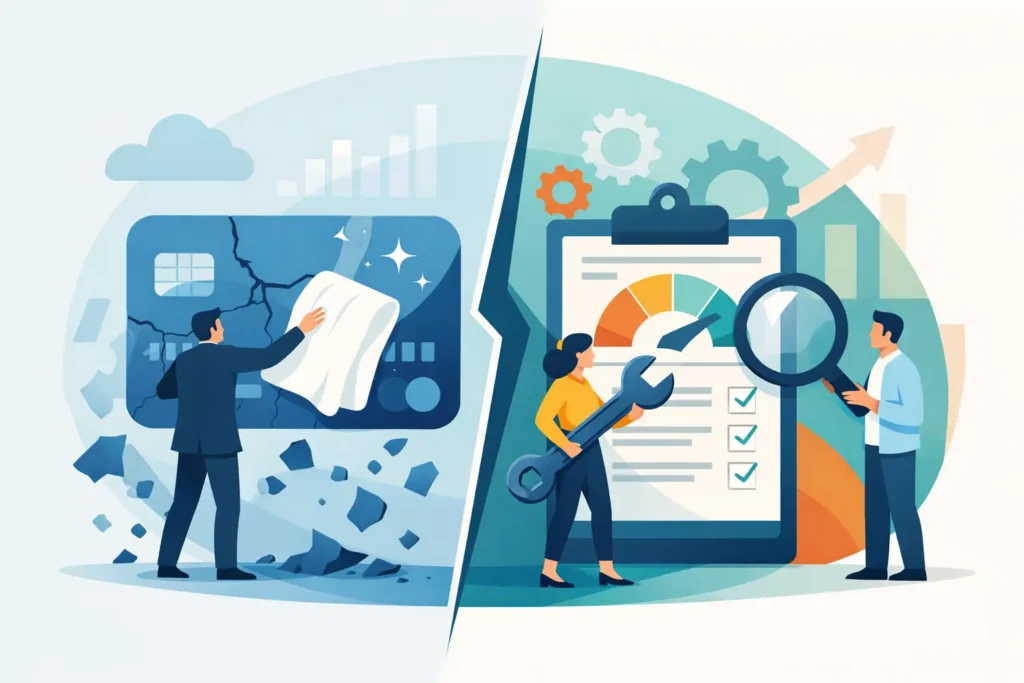
A low credit score can cost you thousands when you are trying to buy a home, finance a car, or qualify for a card with a reasonable rate. That is why the choice between credit wipe vs credit repair matters. One approach is often advertised as a fast reset. The other focuses on reviewing your report, challenging questionable information, and building stronger credit habits. Only one is grounded in the way credit reporting actually works.
If someone promises to erase every negative item, give you a brand-new credit identity, or guarantee a specific score by next week, slow down. Better Scores. Bigger Savings. But real improvement comes from accurate reporting, smart account management, and a clear plan.
Credit Wipe vs Credit Repair: The Core Difference
A so-called credit wipe usually means a promise to remove all negative information from a credit report, regardless of whether it is accurate. The phrase is not an official credit-industry process. It is mostly marketing language, and in some cases it can lead consumers toward dishonest or illegal tactics.
Credit repair is different. It is the process of reviewing your credit reports, identifying inaccurate, incomplete, outdated, or questionable reporting, and disputing information that cannot be verified or is being reported incorrectly. It also includes practical score-improvement guidance, such as lowering credit card balances and protecting your payment history.
The difference comes down to accuracy. Accurate negative information generally cannot be legally removed just because it is hurting your score. A late payment that was reported correctly, for example, may remain for the applicable reporting period. A collection account with the wrong balance, wrong dates, duplicate reporting, or no proper verification may deserve a closer look.
That does not mean you should accept every negative item without question. Credit reports contain errors more often than many people realize. Names, addresses, balances, account statuses, payment history, and inquiry details all need to be reviewed carefully.
Why a “Full Credit Wipe” Can Create Bigger Problems
The appeal is easy to understand. When a mortgage lender says your score needs improvement, you want a solution now, not a lecture about patience. But a company that says it can wipe out legitimate debts or remove everything negative should raise serious concerns.
Some credit-wipe promotions encourage consumers to dispute every account whether the information is accurate or not. Others may hint at using a Credit Privacy Number, sometimes called a CPN, instead of a Social Security number. That is not a fresh start. It can expose you to fraud allegations, denied credit applications, and financial damage that is much harder to repair.
Be especially careful if a company does any of the following:
- Guarantees that all negative accounts will disappear
- Tells you not to contact the credit bureaus yourself
- Asks you to create a new identity or use a CPN
- Demands large upfront fees before providing clear services
- Tells you to provide false information on a credit application
A legitimate service should explain what it is reviewing, why an item may be disputed, and what results are realistic. No honest company can promise that accurate negative information will vanish. Your credit file is not supposed to be erased. It is supposed to be accurate.
What Legitimate Credit Repair Can Do
Credit repair works best when it combines careful report review with action on the factors you can control. The goal is not to pretend a financial problem never happened. The goal is to make sure lenders see a report that is fair, accurate, and supported by the strongest possible current credit behavior.
A proper review can identify issues such as collections that do not belong to you, accounts reported more than once, incorrect late-payment histories, inaccurate charge-off balances, accounts with the wrong status, or inquiries that you did not authorize. These items can affect your score and may affect how an underwriter views your application.
The dispute process can involve the credit bureaus, furnishers of the information, or both. Documentation matters. Account statements, payment confirmations, settlement records, identity-theft reports, and correspondence may help support a dispute when applicable. The process takes follow-through, and outcomes depend on the facts of each account.
Credit repair also looks beyond negative accounts. A consumer with no collections may still have a score problem because credit card utilization is too high, payment history is too thin, or too many recent applications are appearing on the report. A good strategy identifies the most important score barriers instead of treating every client the same way.
When Credit Repair May Help Most
Credit repair can be especially useful before a major financial move. Homebuyers often discover credit problems after they have already found a house they want. By then, a late payment, collection, high card balance, or reporting error can affect loan options and interest costs.
Real estate agents and mortgage brokers also see this situation often. A buyer may be close to qualifying but needs a stronger profile before the lender can move forward. The right review can help identify whether the immediate opportunity is a dispute, a utilization reduction, a payment-history strategy, or simply time for recent positive activity to report.
It can also help consumers who feel overwhelmed by a report with several different problems. A repossession, bankruptcy, foreclosure, charge-off, or collection may not all be handled the same way. Each account has its own dates, status, ownership, and reporting details. Treating them as one big “bad credit” label can lead to missed opportunities.
What You Can Do While Disputes Are Pending
Disputing questionable information is only one part of the plan. The actions you take this month can matter just as much as the accounts you are challenging.
Pay every current account on time. Payment history has a major impact on your credit profile, and one new late payment can work against the progress you are trying to make. If you are struggling, contact the creditor before you miss the due date and ask what options are available.
Keep revolving balances as low as you can. High utilization can make scores drop even when you have never missed a payment. If possible, pay down balances before the statement closing date, not only by the payment due date. This may help a lower balance report to the credit bureaus.
Avoid opening several new accounts just to chase a score increase. New applications and new accounts can be helpful in limited situations, but they can also create more inquiries and reduce the average age of your accounts. It depends on your existing credit profile and your immediate goal.
Do not close older credit cards without a reason. Closing an account can reduce available credit and increase utilization. If the account has no annual fee and you can manage it responsibly, keeping it open may support a more established credit profile.
How to Choose a Credit Repair Service
A credit repair service should make the process understandable. You deserve to know what is being reviewed, what the possible next steps are, and what you can do personally to support progress.
Look for clear pricing, straightforward communication, and realistic expectations. Ask whether the company reviews all three major credit reports, whether it explains disputed items in plain language, and whether it provides guidance for positive credit-building habits. You should never feel pressured to sign up before you understand the service.
At Paralegal Credit Fix, the process starts with a free, no-obligation credit report analysis. That gives you a chance to understand the damaging items on your report, the positive factors already working in your favor, and the practical steps that may help strengthen your profile.
The Better Question Is Not “Can Everything Be Removed?”
The better question is: what is hurting your score, what is accurate, what may be questionable, and what can you improve right now? That is where real progress begins.
A credit wipe promise may sound fast, but it can leave you with false expectations or worse. Credit repair takes a more honest path. It focuses on accuracy, documentation, smart disputes, lower utilization, on-time payments, and a plan built around your financial goal.
Do not wait until a lender says no to find out what is on your credit report. Review it now, ask questions about what you do not understand, and take the next right step. A stronger credit profile is built one accurate correction and one responsible decision at a time.
Pingback: 7 Best Steps Before Mortgage Preapproval - Paralegal Credit Fix